
Finance & Cash Flow
The month the money stops is rarely announced in advance.
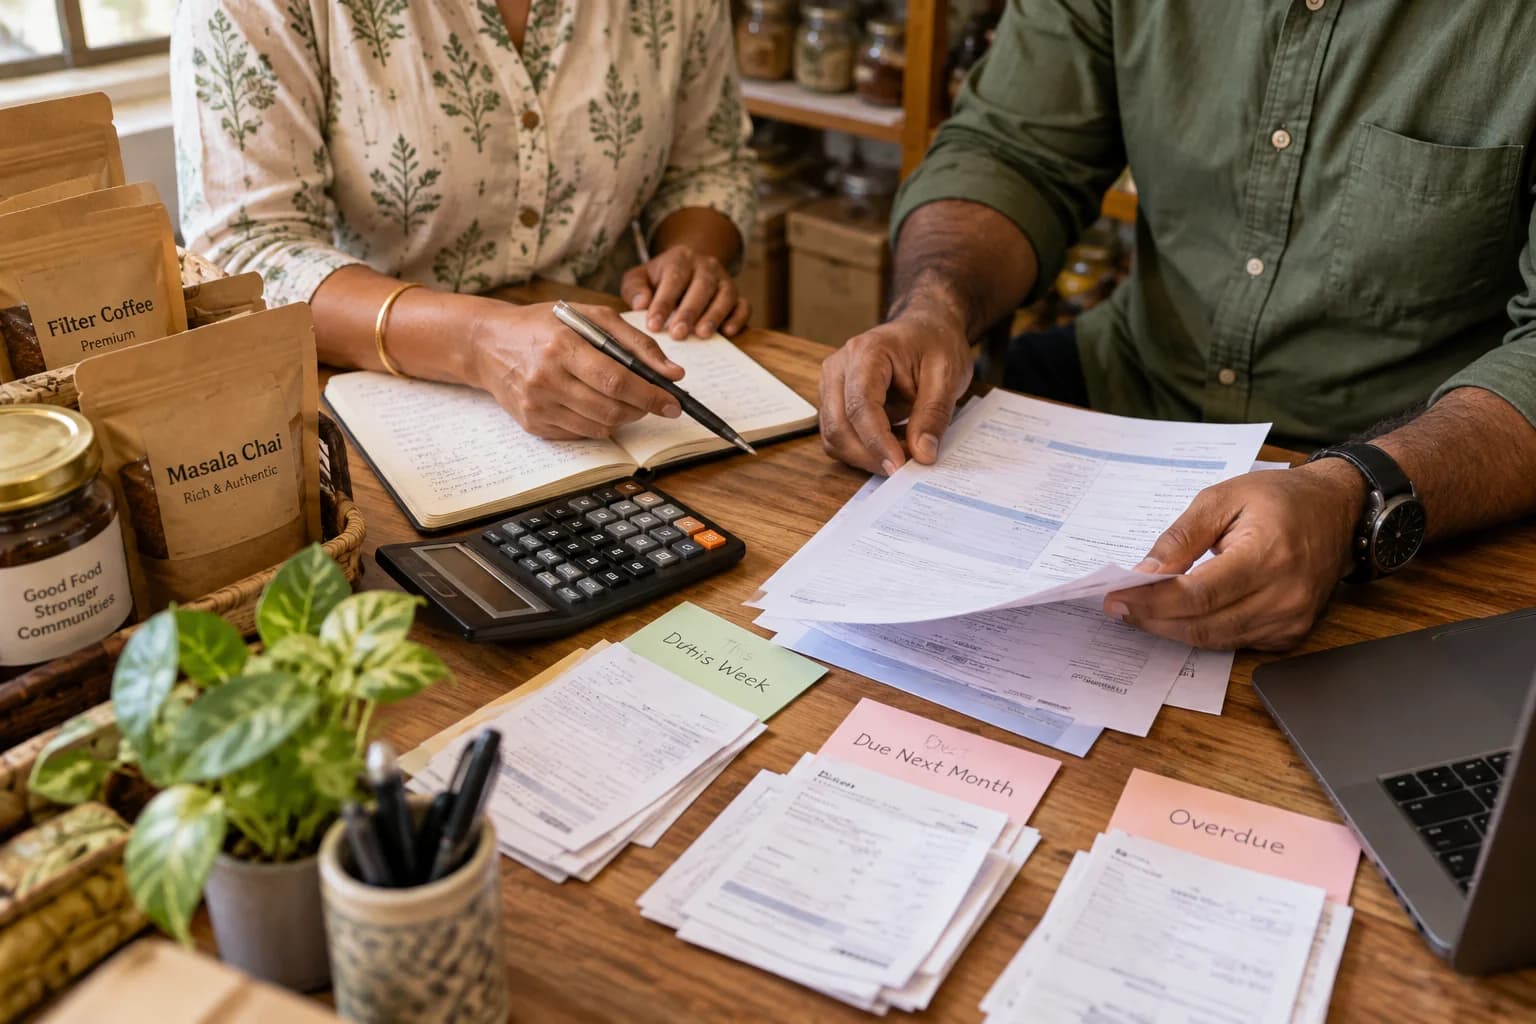
A payment delayed by a big customer, a sudden repair, a slow season or an illness in the family: most businesses meet one of these sooner or later. Those with a cushion absorb it. Those without borrow in a hurry, delay payments or sell at a discount. This session helps an owner work out what a reasonable cushion looks like for their own business and how to build it in small steps.
Explore this page7 sections
A reserve is not idle money. It is what lets you make decisions calmly.
A cash reserve buys time. With it, a delayed payment is an irritation; without it, the same delay is a crisis. Owners with a cushion can say no to a bad deal, wait for a better price or hold back from a panicked loan. Owners without one are forced into whichever choice is fastest.
Owners often say they would build a reserve if there were any surplus. In practice, a reserve is built by deciding to set aside something first, in small amounts, the way a person pays an instalment. There is no single right size. It depends on how steady the sales are, how quickly customers pay, how big the fixed costs are and how exposed the business is to a few customers or a season. The session helps owners reason it out rather than copy a rule of thumb.
What the session covers
30 topics across 6 areas. Six steps from understanding the need to building the reserve.
What Must Be Paid Whatever HappensThe fixed commitments.5
Each participant lists their own commitments and arrives at a monthly figure. For many owners this is the first time the number has been written down in one place.
- Rent, salaries, loan instalments and utilities
- Statutory and tax payments that fall due regardless of sales
- Supplier payments already committed
- Owner's own minimum living needs from the business
- Adding it up as a monthly figure
How Much Cushion Is Enough?There is no universal answer, only a way to reason.5
- Covering a number of weeks of commitments, and how to choose the number
- How steady or seasonal the sales are
- How long customers take to pay
- How dependent the business is on a few customers
- Different needs for a shop, a service business and a manufacturer
Rules of thumb found online were not written for your business. Treat them as a starting question, not a target.
Stress-Testing the BusinessThree ordinary bad scenarios.5
An illustration (made-up, round numbers): monthly commitments of 2 lakh rupees and 3 lakh rupees in cash cover about six weeks of costs. If the biggest customer's payment of 1.5 lakh rupees is delayed by two months, the picture changes, and participants work through the same logic with their own figures.
- Sales fall by a fixed share for a few months
- The biggest customer pays two months late
- A major, unplanned expense arrives
- How many weeks the current cash lasts in each case
- What would be cut first, and what would be protected
Building It in Small StepsConsistency beats size.5
- Setting aside a small fixed amount or share each week or month
- Treating it like an instalment, not a leftover
- Using good months, and unexpected inflows, to top up
- Balancing the reserve against investment in growth
- A realistic timeline, written down
Where to Keep It, and Where Not ToSafe and reachable, not clever.5
- Why a reserve should be easy to reach when needed
- Keeping it separate from the day-to-day account
- Why money in stock, equipment or a friend's hands is not a reserve
- The questions to ask a bank or adviser about suitable places to keep it
- Why this session does not recommend any product
Choosing where to hold funds is a financial decision for the owner and their adviser.
Rules for Using and Refilling ItSo the reserve is there when it is needed.5
- What counts as a genuine reason to use it
- Who decides, in a business with partners
- How to refill it after use
- What to do if it has been used and not refilled
- Reviewing the target each year, or when the business changes
What participants leave with
- Their own monthly commitments figure
- A target reserve and the reasoning behind it
- A savings plan with a first amount and a first date
- A short set of rules for using and refilling the reserve
- Questions to take to an adviser or their bank
What this session is not
- A recommendation of any savings or investment product
- A rule that every business must hold a fixed number of months
- Investment or personal financial advice
- A claim that a reserve protects a business from every shock
Who teaches it
- Chartered accountants and finance practitioners who work with small businesses
- Owners who came through a hard month and can describe what helped
- Finance managers from small and medium businesses
How the session runs
Two hours, in a small group, with pen and paper or a laptop. The practitioner explains the reasoning, then participants work on their own commitments, stress tests and first savings step, with help on request. The made-up illustrations are labelled and use round figures. The session gives general education and does not replace individual accounting, tax or financial advice.
What your students leave with
- A list of their own business's fixed monthly commitments
- A way to work out how many weeks of costs a given amount of cash would cover
- A target cushion for their own business, with the reasoning written down
- A realistic plan to build it in small, regular steps
- Rules for when the reserve may be used and how it is topped up again
- An understanding of where reserve money can sensibly be kept, and the questions to ask an adviser
Scheduled sessions
Nothing scheduled yet
Sessions are arranged with a college once a date is agreed. Ask us and we will find the right person for it.
A student rather than a college? See what is coming up, or ask your placement team to host this.
Build the cushion before the bad month, not during it.
Tell us who your students are and what stage they are at. Sessions are free for participants.